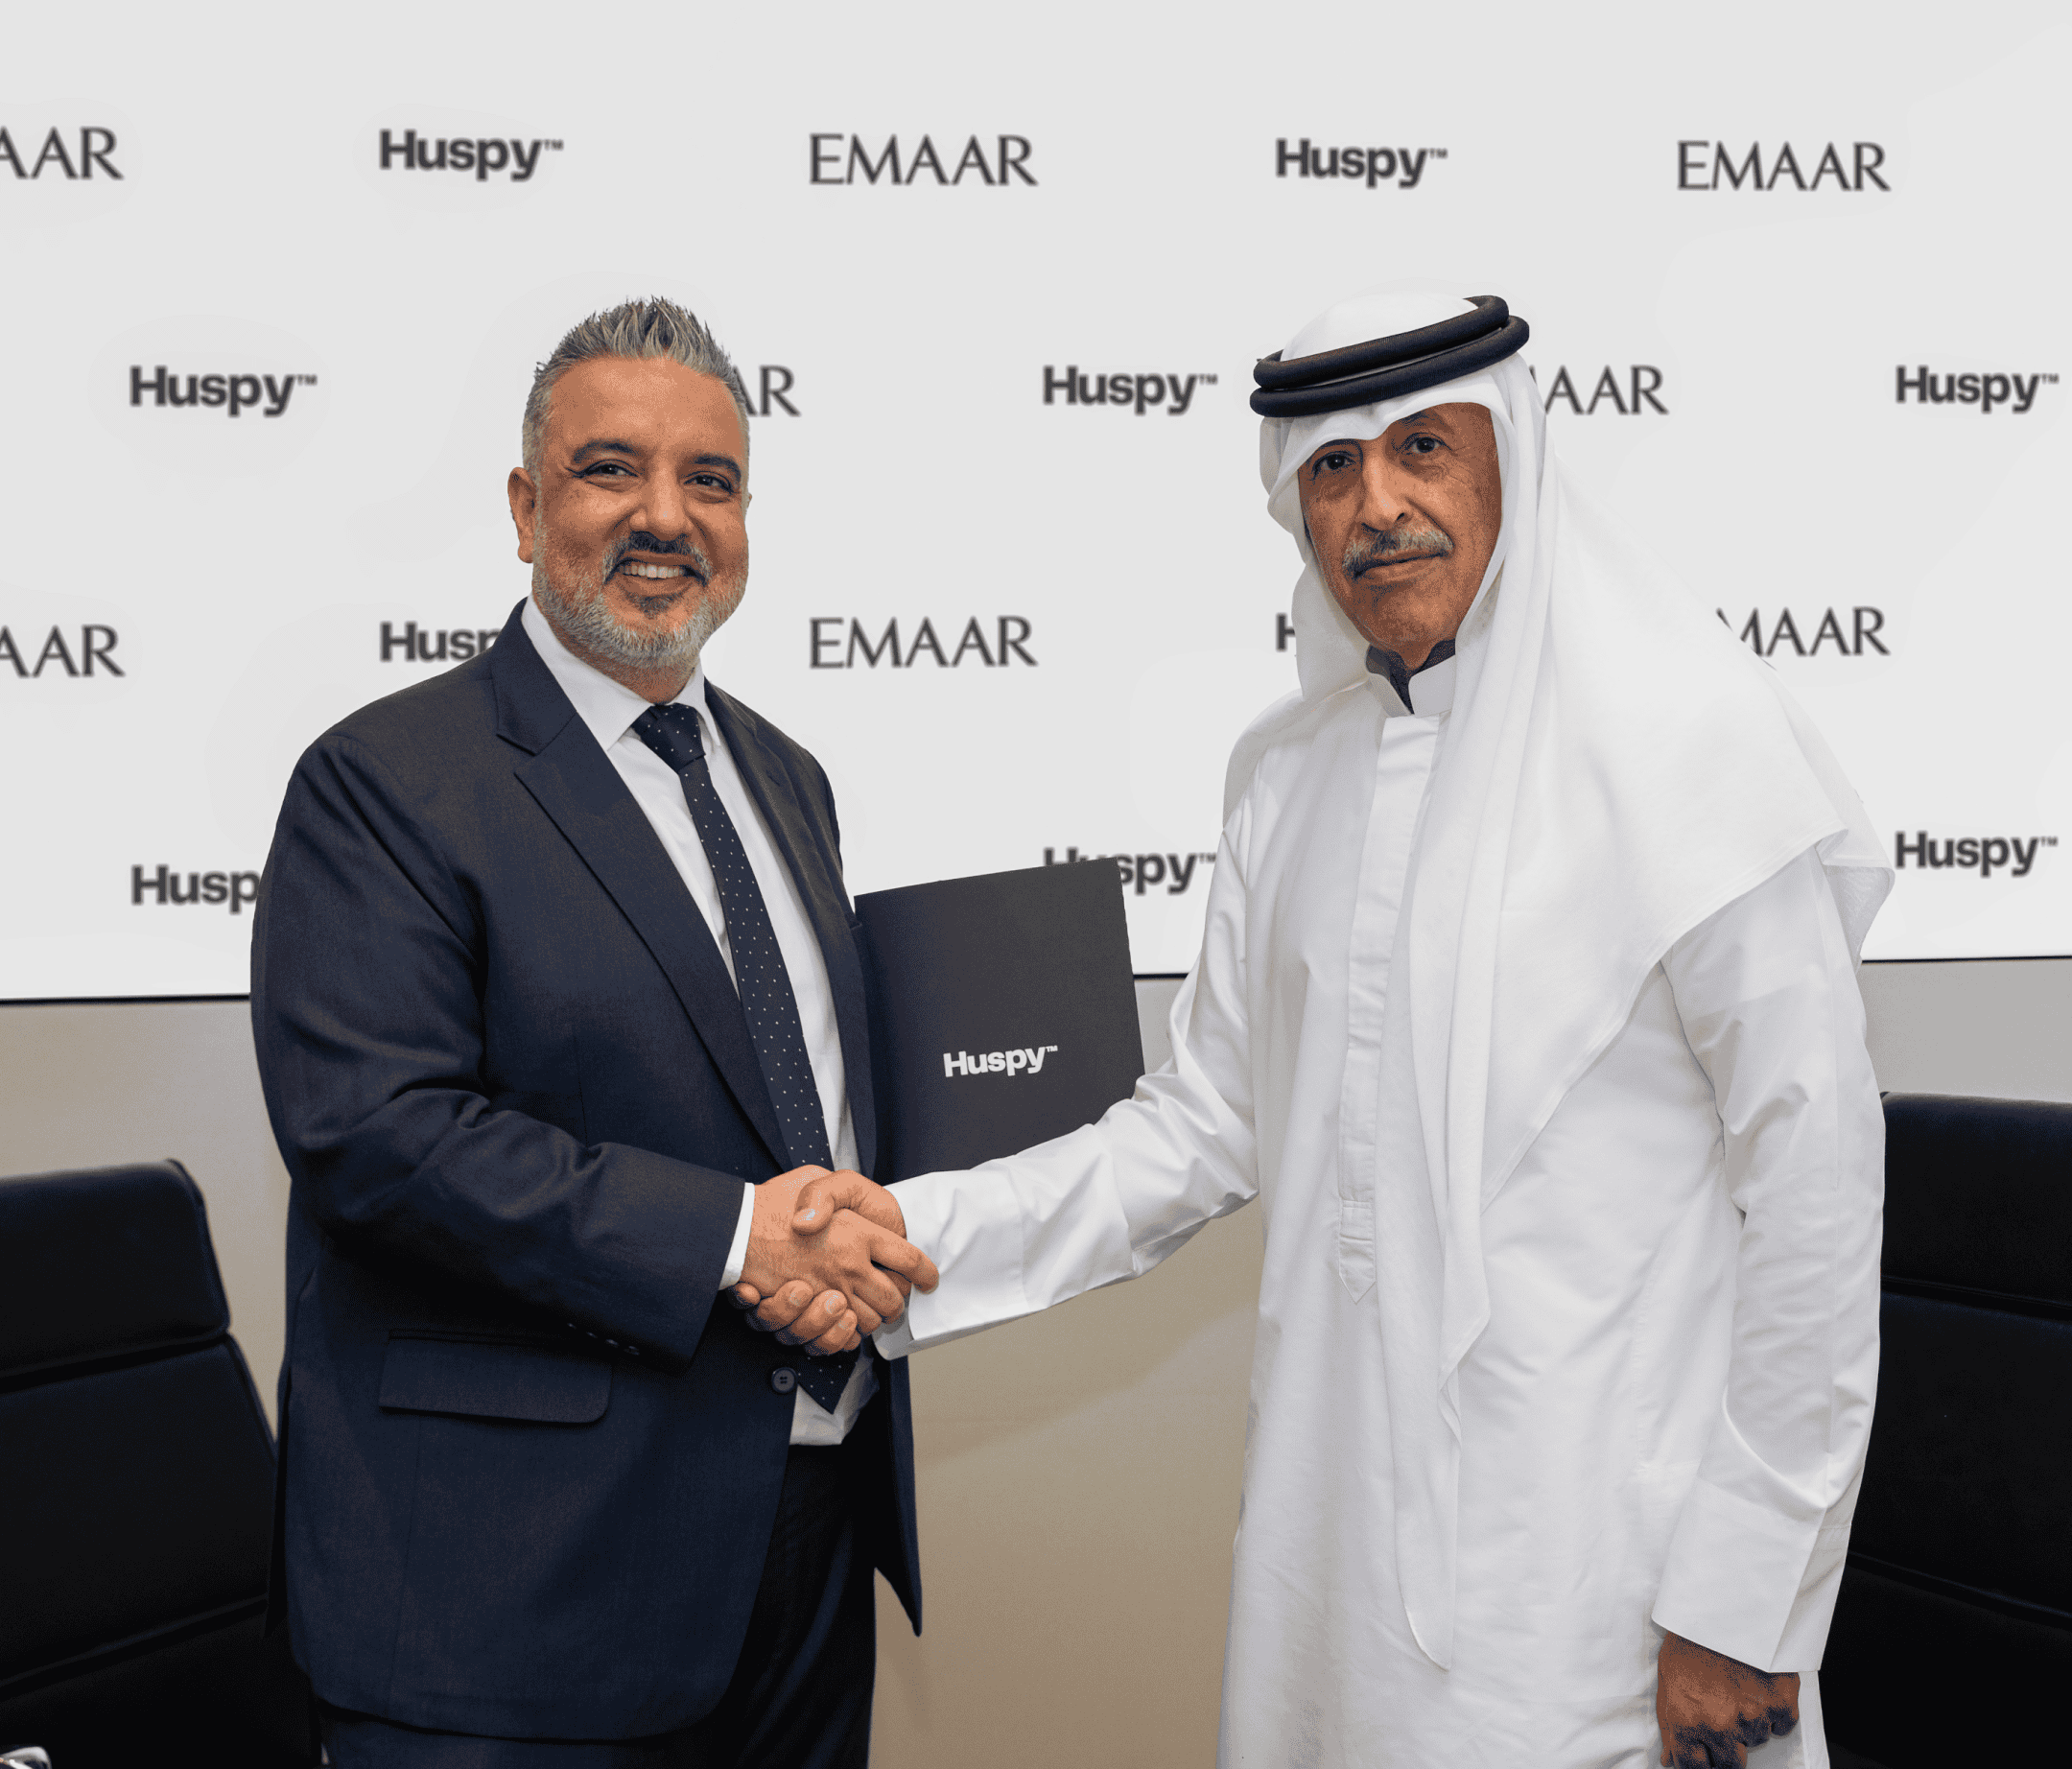
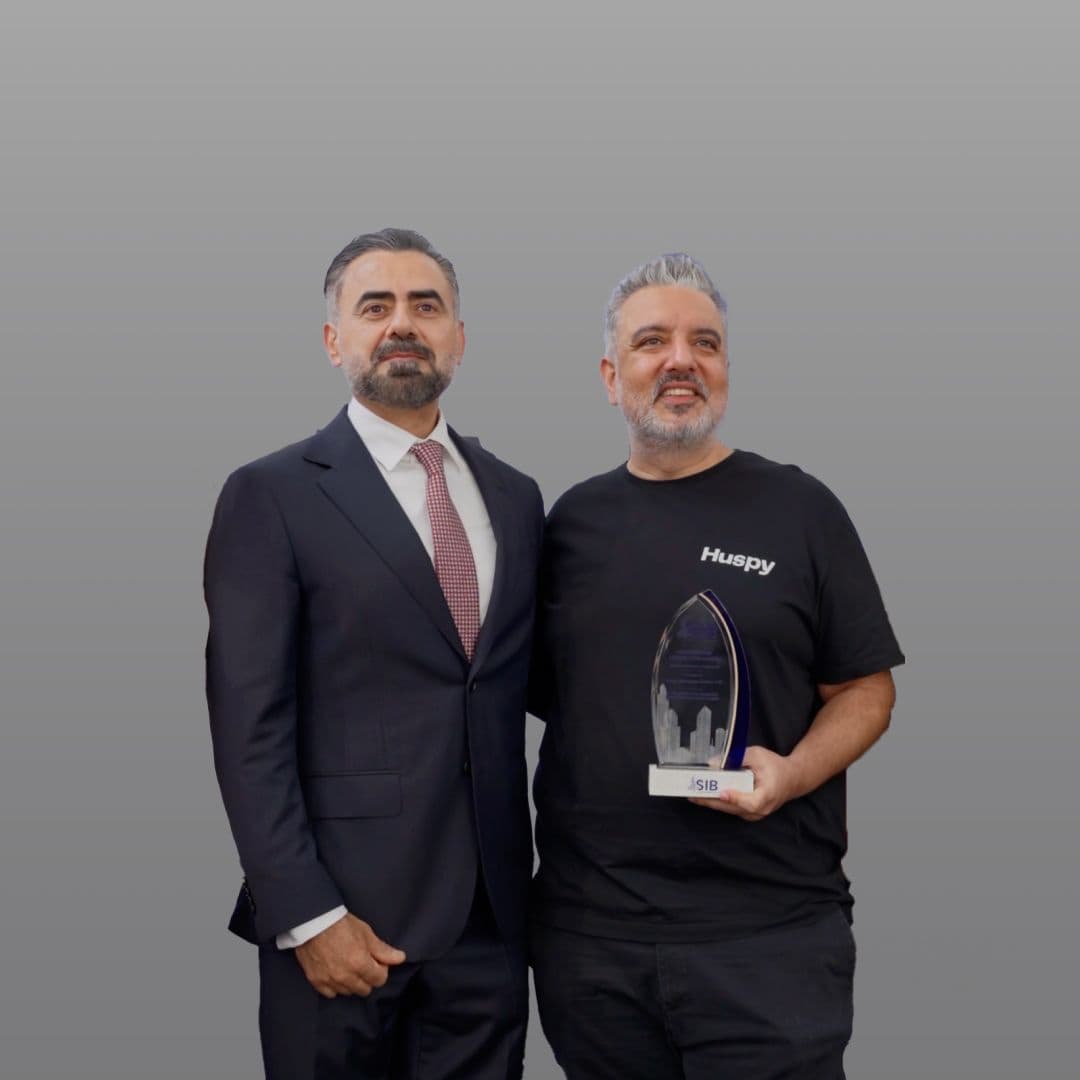
Huspy has received the Partnership Distinction Award from Sharjah Islamic Bank (SIB), recognising its continued collaboration and contribution to the growth of the bank’s Real Estate Finance division. The recognition highlights a banking relationship that supports Huspy’s work as a UAE mortgage provider, helping buyers understand their home-financing options.
- Sharjah Islamic Bank recognised Huspy with its Partnership Distinction Award for collaboration with its Real Estate Finance division.
- Huspy’s UAE mortgage provider services connect buyers with financing options across an established banking network.
- Luxury-property financing requires attention to income, liquidity, property valuation and repayment flexibility—not the headline rate alone.
- Huspy Signature connects luxury-property advisory with access to Huspy’s mortgage services; lending decisions remain with each bank.
For buyers exploring UAE mortgages, the value of a banking relationship lies in the practical guidance behind it: understanding which lenders accept their circumstances, what evidence an application requires and how financing fits the intended purchase.

A partnership built on shared ambition
The Partnership Distinction Award recognises the collaboration between Huspy and Sharjah Islamic Bank and the contribution of both teams to SIB’s Real Estate Finance division.
Strong relationships between mortgage advisers and banks support the work behind a home purchase. An adviser needs to understand the applicant’s circumstances and the bank’s requirements; the bank needs a clear, properly documented application on which to base its assessment.
Huspy’s collaboration with SIB brings together mortgage advisory capabilities, a technology-led approach and the bank’s real estate finance expertise. The award marks a milestone in that relationship and provides a foundation for continued collaboration.
For customers, the distinction is meaningful as recognition of the partnership. It should not be confused with a guarantee of approval, a particular financing offer or preferential treatment for every application.
Why this matters for luxury-property buyers
An exceptional home deserves a financing decision considered with equal care. For high-net-worth and ultra-high-net-worth buyers, the discussion can extend beyond monthly affordability to the capital committed at completion, the income a lender will recognise and the flexibility needed during ownership.
A buyer with international earnings, business interests or several properties should establish how a prospective lender assesses those circumstances before relying on a borrowing estimate. Significant assets do not remove the need for income verification, property valuation or a documented source of funds.
Huspy Signature connects luxury-property buyers with local property expertise and access to Huspy’s mortgage advisory services. That connection helps bring the property search and financing discussion into the same purchase plan, while keeping the bank’s lending decision separate.
The practical objective is not simply to obtain the largest available mortgage. It is to understand whether the proposed financing suits the property, the buyer’s circumstances and the intended ownership period.
Huspy’s position in the UAE mortgage market
Choosing a UAE mortgage provider requires a clear distinction between the adviser arranging the application and the bank providing the finance. Huspy works with banking partners to help customers assess and arrange mortgages; the lender determines eligibility, approves the facility and sets its contractual conditions.
Huspy Signature’s mortgage information describes established relationships with more than 20 banks. A broad network provides a basis for comparing lender requirements rather than treating one bank’s assessment as representative of the entire market.
In a company announcement dated 16 September 2026, Huspy reported handling approximately 25% of residential mortgages in the UAE. This is a company-reported measure of market presence, not an independent ranking of every lender or mortgage adviser.
The SIB award adds a different form of recognition: acknowledgement from a banking partner of a specific collaboration. Market presence and a partnership award provide useful context, but the right financing decision still depends on your individual application.
What strong banking relationships mean for customers
A broader basis for lender selection
Banks differ in how they assess residency, income, employment, property type and financing requirements. Approaching a single institution establishes what that lender can offer; comparing suitable lenders gives you a wider basis for making a decision.
Huspy’s mortgage experts assess the customer’s circumstances and help identify relevant financing options. The appropriate shortlist is the one that fits the application—not necessarily every bank in the network.
Better preparation for the application
A well-prepared application explains the borrower’s financial position and provides the evidence the lender requests. For buyers with overseas income or business ownership, establishing the document requirements early is particularly useful.
Ask which income sources will be considered, what supporting records are needed and whether any translations or certifications are required. A clear checklist is more useful than assuming a previous bank application will satisfy a different institution.
A clearer comparison of financing terms
An attractive introductory rate is only part of the decision. You also need to understand how repayments change, which charges apply and what happens if you sell, refinance or repay part of the borrowing.
Compare proposals on equivalent assumptions. Different borrowing amounts or repayment periods can make one offer appear more attractive without improving the overall fit.
Banking relationships support these discussions. They do not remove the need to read the written offer or obtain independent advice where your wider legal, tax or financial position requires it.
Financing considerations for substantial property purchases
For an ultra-high-net-worth buyer, the financing brief should describe the intended transaction accurately without assuming that wealth alone determines eligibility. Establish the following points before making a mortgage-dependent commitment.
- Income assessment: identify the earnings the lender will recognise and the evidence required. Business turnover, personal income and investment assets are not interchangeable measures.
- Capital commitment: separate the deposit, transaction expenses and cash reserves from the proposed mortgage advance. Confirm when each payment becomes due.
- Property acceptance: establish whether the bank will finance the selected home and how its valuation affects the advance.
- Repayment structure: understand the initial terms, subsequent payment calculation and the effect of changing the repayment period.
- Ownership plans: disclose the intended borrower and ownership arrangement early so the lender and legal adviser can assess its acceptability.
- Exit flexibility: review the contractual treatment of partial repayment, sale and refinancing before accepting the facility.
For a buyer considering a Palm Jumeirah villa or a Saadiyat Island residence, the address is only one part of the assessment. The lender must accept the specific property and the borrower’s financial profile; a premium location does not establish that financing is available.
International buyers should also distinguish the currency of their earnings from the currency of their repayments. Discuss the implications with an appropriately qualified adviser rather than assuming an exchange rate will remain unchanged.
Mortgage services through Huspy
Huspy supports customers at different stages of property ownership, including resident purchases, non-resident purchases, refinancing and equity release. These routes serve different needs and should not be treated as interchangeable.
| Financing route | Best for | Main purpose | Key consideration |
|---|---|---|---|
| Resident mortgage | UAE residents purchasing a property | Arrange borrowing for an eligible home purchase | Approval depends on the borrower, property and lender’s criteria |
| Non-resident mortgage | Overseas buyers purchasing in the UAE | Explore lenders that accept non-resident applicants | Accepted residence countries, income and documentation vary |
| Refinancing | Owners reviewing an existing mortgage | Assess replacement borrowing or a move to another lender | Switching costs and the full repayment terms must be compared |
| Equity release | Owners seeking borrowing against existing property equity | Assess whether property-backed capital is available | Additional borrowing requires approval and creates repayment obligations |
Resident mortgages
Huspy helps UAE residents explore mortgage options based on their financial profile and property requirements. Mortgage experts guide customers through eligibility, bank selection, documentation, approval and disbursement.
Resident status does not establish a universal borrowing amount or repayment term. Ask for an assessment that reflects your recognised income, existing commitments and chosen property.
Non-resident mortgages
Buyers living outside the UAE can explore mortgage options with lenders that accept non-resident applications. Requirements and financing terms depend on the institution and the applicant’s circumstances.
Confirm eligibility before making assumptions based on resident products. Your country of residence, income source and proposed property should form part of the initial discussion.
Refinancing
An existing mortgage deserves review when your circumstances or ownership plans change. Huspy can help compare available refinancing options and guide customers through the process.
A lower monthly instalment does not automatically mean lower total borrowing costs. Check the remaining balance, replacement term, settlement requirements and applicable charges together.
Equity release
Property owners can ask whether they qualify to borrow against equity in an existing home, subject to lender eligibility and valuation requirements. Huspy’s mortgage experts can help assess available options and explain the application process.
Released equity is borrowed money, not additional income. Confirm the approved amount, permitted use and disbursement conditions before relying on it for another commitment.
From the first financing discussion to completion
A considered application separates an initial borrowing assessment from final approval and the release of funds. Each stage answers a different question.
- Define the purchase brief. Identify the intended property, ownership purpose, residency position and approximate financing requirement.
- Assess suitable lenders. Establish which institutions accept your circumstances and request their application requirements.
- Prepare the financial file. Provide the requested identification, income and banking evidence through the agreed application channel.
- Review the borrowing assessment. Read the conditions and validity of any pre-approval; identify what remains outstanding.
- Complete property and final-offer checks. Reconcile the valuation, approved advance and cash contribution before relying on the proposed funding.
- Coordinate completion. Confirm the remaining conditions, required payments and disbursement sequence with the responsible parties.
Pre-approval is not a guarantee of financing for a particular property. Keeping that distinction clear protects the quality of the purchase decision without understating the usefulness of early lender assessment.
Continuing the collaboration with Sharjah Islamic Bank
The Partnership Distinction Award is a recognition of the work Huspy and Sharjah Islamic Bank have undertaken together. It reflects a relationship built on trust, shared ambition and a commitment to supporting the development of real estate finance.
For Huspy Signature clients, the relevance is practical: luxury-property advisory is strengthened when the financing discussion is informed, specific and connected to the intended purchase. Huspy looks forward to building on its collaboration with SIB and creating further milestones together.
FAQ
What award did Huspy receive from Sharjah Islamic Bank?
Huspy received the Partnership Distinction Award from Sharjah Islamic Bank (SIB). The award recognises its continued collaboration and contribution to the growth of SIB’s Real Estate Finance division.
What does the SIB award mean for mortgage customers?
The SIB award recognises a banking partnership, not an individual mortgage approval or guaranteed offer. Customers still need a lender-specific assessment of their circumstances and selected property.
Is Huspy a bank or a mortgage adviser?
Huspy provides mortgage advisory and arrangement services through its banking relationships. The bank providing the finance makes the lending decision and sets the approved facility’s terms.
Can ultra-high-net-worth buyers get help with UAE property financing?
Huspy Signature connects luxury-property buyers with property advisory and access to Huspy’s mortgage services. Buyers with substantial assets or international income still need to satisfy the chosen lender’s eligibility and documentation requirements.
Can buyers living outside the UAE apply for a mortgage through Huspy?
Huspy helps non-resident buyers explore UAE mortgage options with lenders that accept their circumstances. Eligibility, documentation and financing terms vary by bank and applicant.
Does Huspy help with refinancing and equity release?
Huspy helps property owners assess refinancing and equity-release options, subject to lender criteria and valuation. Refinancing does not automatically release cash, and equity release creates additional borrowing obligations.
Does a strong bank partnership guarantee the best mortgage?
No, a bank partnership does not establish that one mortgage is best for every buyer. Compare suitable offers using the full repayment terms, costs, eligibility requirements and your intended ownership plans.
A considered next step
For a substantial property purchase, ask for the complete funding plan—not simply the largest mortgage figure. Bring the proposed advance, cash contribution, completion conditions and repayment commitments into one discussion before committing.
To discuss a luxury-property purchase and your financing requirements, start a private conversation with Huspy Signature.
Mortgage availability and approval are subject to the lender’s criteria, property valuation and final terms. This article provides general information, not individual financial, legal or tax advice.